
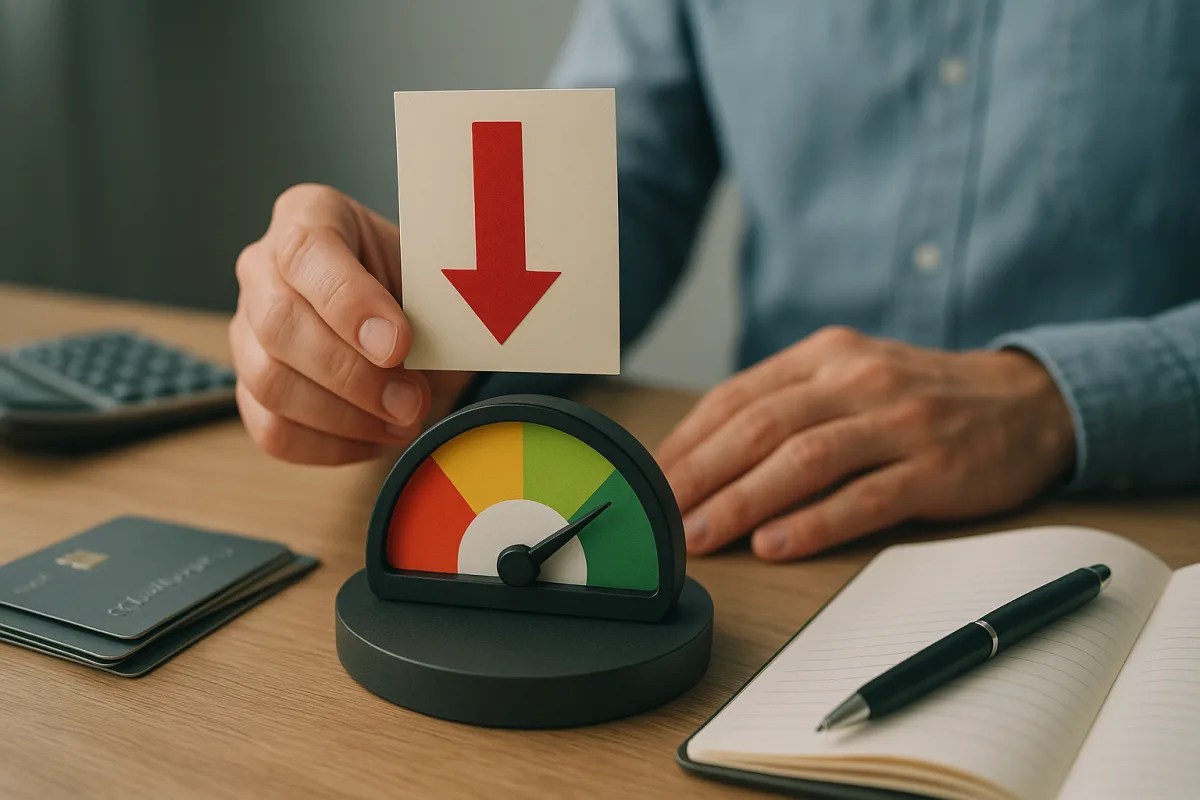
Why does a credit score matter?
A credit score is one of the key indicators used to assess a person's debt repayment habits and overall financial behavior. In everyday use, the score tracked through Findeks can be taken into account in many areas, from new loan applications to credit card limit reviews.
A drop in this score may not be caused by just one factor. In many cases, payment delays, rising debt burdens, heavy use of credit limits and a series of new applications over a short period can combine to increase the perceived risk.
What are the main reasons a credit score falls?
Problems in debt repayment discipline are among the most important factors that weaken a credit score. Paying less than the minimum amount due, missing the due date or falling behind again on restructured debt can all have a negative impact.
In addition, the total burden of products such as credit cards and personal loans becoming heavy relative to income also stands out. Continuously using credit card limits at high levels can be interpreted as pressure on a person's cash flow.
Frequent applications and irregular financial activity
Back-to-back applications for loans or credit cards over a short period can also create a risky profile. That is because this pattern may suggest a growing need for new financing. Irregular account activity, bounced payment issues or debts that enter collections can also leave lasting marks on a person's financial history.
- Payments are delayed or missed
- Credit card limits are used heavily
- Too many applications are made in a short time
- Existing debts become disproportionate to income
How can a credit score be improved quickly?
The first step is to clearly see all debts and payment dates. Creating a regular repayment plan, setting up automatic payment instructions and prioritizing overdue debts form the basis of the recovery process.
Second, it is important to bring credit card usage down to a more balanced level. Paying the full card balance, or as much of it as possible, on time can help prevent new delays. Avoiding unnecessary new applications during the same period also helps create a healthier profile.
Realistic and sustainable steps
A credit score usually does not rise suddenly with one move; improvement is often a regular and patient process. For that reason, budgeting, keeping spending under control and borrowing in line with income are among the most effective methods.
- Focus first on paying off overdue debts
- Delay new loan applications unless absolutely necessary
- Keep credit limit usage under better control
- Maintain a stable payment pattern for several periods
In short, once the cause of a credit score drop is identified correctly, it becomes possible to draw up a healthier recovery plan. Rather than expecting quick results, a steady payment habit and a disciplined approach to borrowing can support a stronger financial profile over the long term.
"""
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.