
Why are young workers opting out of pension plans?
Workplace pension plans in the UK have come under renewed scrutiny, especially among younger workers, as living costs continue to rise. In examples reported by BBC Business, some employees are choosing to temporarily stop saving for retirement because of rent, student loans, transport costs and family expenses.
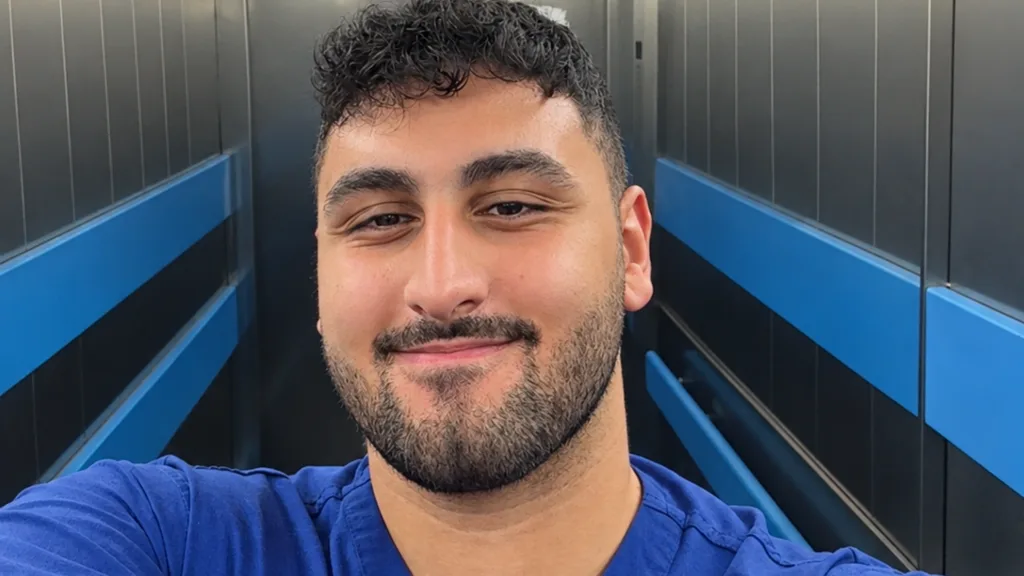
Hassan Nassar, a 26-year-old trainee doctor working in the West Midlands, said he had been paying about £430 a month into his NHS workplace pension plan until early September, but decided to pause his contributions for six to 12 months because of financial strain. Nassar said the move was driven by support for a sick family member, saving for his first home, rent and student loan payments, and estimated it could leave him with around £5,000 to £10,000 less in retirement income in the long run.
What is the financial benefit of staying in the system?
In the UK, workers aged 22 and over who earn more than £10,000 a year are generally automatically enrolled in a workplace pension scheme. A worker typically contributes around 5% of pay, tax relief is added and the employer also makes a minimum contribution.
- Employee contributions are deducted automatically from salary.
- Employer contributions and tax relief make saving more powerful than putting money aside alone.
Nassar said he was contributing 10.7% of his gross monthly income and that the NHS was also adding a significant amount on top. But unlike some employers, the NHS does not allow workers to reduce their contribution rate during difficult periods, which also influenced his decision.
What do the official figures and experts say?
According to data from the Department for Work and Pensions (DWP), around 22.6 million people covered by automatic enrolment — or 90% of those eligible — are still paying into the system. By contrast, about 2.5 million people are outside the scheme.
Pensions Minister Torsten Bell said the number of young workers not saving is rising, and that today’s young people risk ending up with lower private pension income than today’s retirees. That risk matters even more because the state pension only provides a basic level of income.
Why is the loss of compound growth so critical?
April Leeson of financial advice firm The Private Office stressed that pension contributions should not be cut completely if it can be avoided. According to Leeson, the loss is not limited to employer contributions; the long-term compound growth on money paid in during your 20s also creates a major advantage.
Leeson said that, given the current minimum pension age of 57, money invested at a young age has at least 30 years to grow. In her example, £100 saved today would be worth significantly more after 30 years at a 4% annual return than the same amount paid in 15 to 20 years later.
Young and middle-aged workers are feeling the same pressure
Evie, a 22-year-old living in Cornwall, said she had not signed up for the pension plan at her London-based events company. Fresh out of drama school, Evie said she could not afford to contribute right now because of food, transport and £800 monthly rent.
The issue is not limited to young people. Kharlee, a 47-year-old teacher in south-east London, said she had stopped making workplace pension contributions twice over the past five years for financial reasons, leaving her with about £5,000 less in retirement savings. Now working as a freelancer, Kharlee said she hopes to return to a private pension plan.
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.