
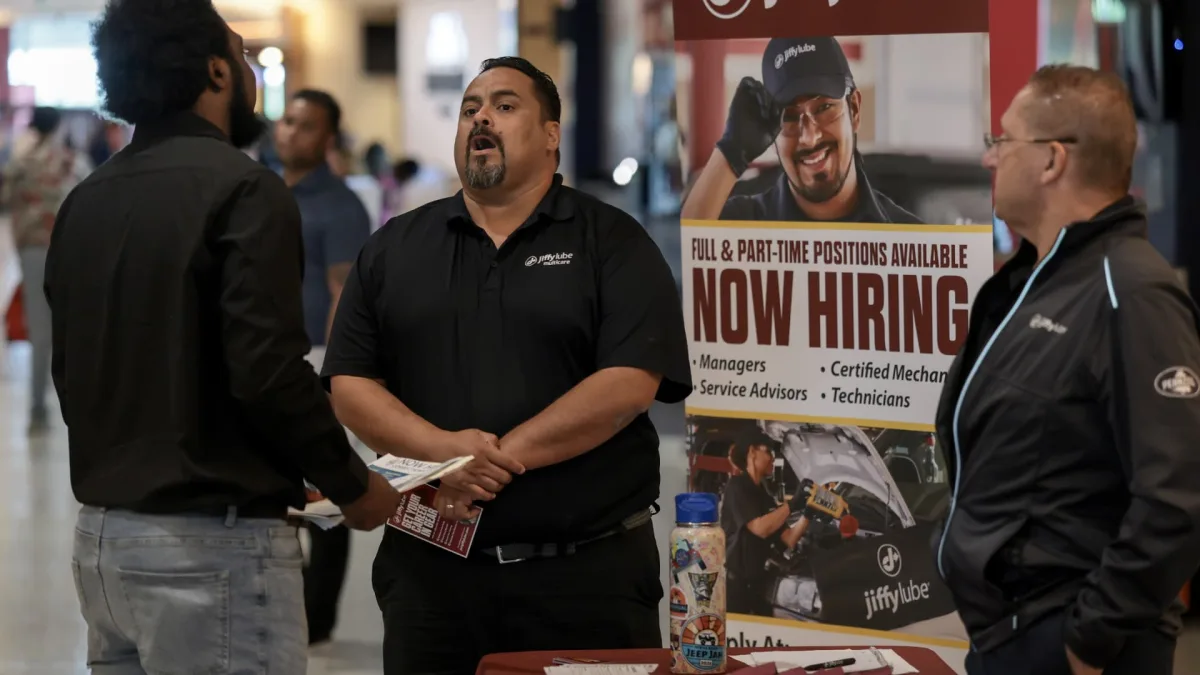
What is the market expecting?
U.S. nonfarm payrolls data due on Friday will show how the labor market performed at the end of summer, with the September report expected to be closely watched. According to the Dow Jones consensus on Wall Street, nonfarm payrolls are seen rising by 84,000, while the unemployment rate is expected to hold at 4.1%. That points to a slowdown compared with stronger hiring periods in previous years, but still suggests an economy that remains near full employment.
The forecast follows August’s gain of 162,000 jobs. That report also included upward revisions to prior months’ figures. As a result, September’s numbers are being treated as an important test of whether late-summer job growth was a temporary pause or part of a more durable slowdown.
Why is the Fed focused on this data?
For the Federal Reserve (Fed), employment data remains one of the key indicators for testing how resilient the economy is while the fight against inflation continues. Fed officials in recent days have pointed to broadly stable labor-market conditions, while shifting more attention to the inflation outlook.
Slower wage growth also supports that view. Average hourly earnings are expected to rise 3.1% year over year in September, down from around 4% earlier in the year. That moderate pace in wage increases is reinforcing views that the urgency for additional policy tightening may be limited.
- Average monthly job growth in 2026 has been 80,000.
- Employment fell by 156,000 in February, while the following month saw job growth rebound to 214,000.
What could this mean for markets and rates?
After this week’s Fed comments, markets have sharply reduced the odds of another rate hike at the October 27-28 meeting. In particular, investors now see a December move as more likely than one in October, following remarks from New York Fed President John Williams that suggested there is no need to rush.
Even so, the labor market is not sending only signs of relief. According to a Glassdoor survey, worker confidence fell to a record low in September, with job security, economic uncertainty, inflation and concerns about artificial intelligence standing out. Meanwhile, initial jobless claims fell to 197,000 last week, and Challenger, Gray & Christmas data showed September layoffs were 18% lower than in August and 20% lower than in the same period last year.
This mixed picture suggests Friday’s report could move Treasury yields, the dollar and stock markets. A stronger-than-expected reading could help keep another Fed rate hike on the table. A weaker report, however, would strengthen expectations that the next move may be pushed back.
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.