
What do the second-quarter figures show?
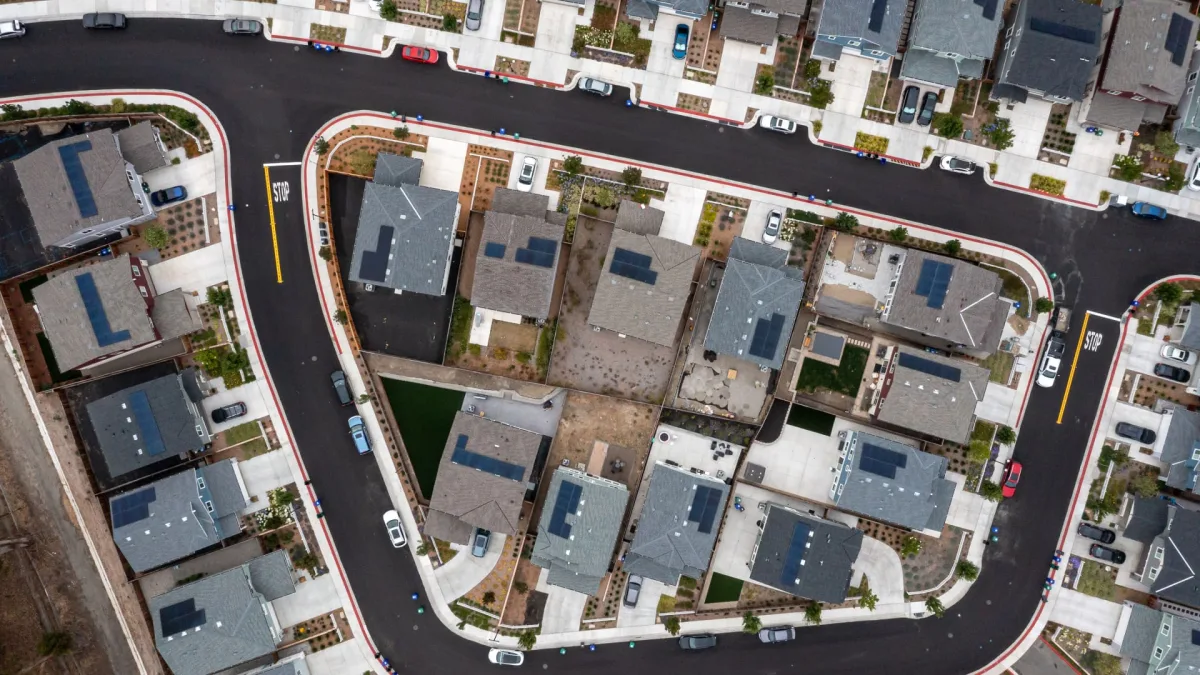
U.S. home equity reached historic highs in the second quarter, boosted by the sharp rise in home prices in recent years. Even so, homeowners are staying cautious about turning that wealth into cash by borrowing against it, leaving most of the accumulated value untouched.
According to Cotality, the amount of equity that could be tapped while keeping the safety margin required by lenders stood at $11.5 trillion. Total home equity among mortgage borrowers rose to $17.9 trillion, while the average per homeowner was calculated at $310,000. That average was up $6,000 from the previous three months.
Usage remains very limited
Second mortgages and home equity lines of credit, or HELOCs, rose by about 20% compared with the first quarter. However, the amount actually used remained below 0.1% of total tappable equity. The figures suggest households remain reluctant to take on new debt despite their large store of wealth.
Why aren’t homeowners borrowing?
According to Thom Malone, borrowers with the most housing wealth are often the least likely to use it. Low mortgage rates, strong cash flow and limited need to move have all been key factors behind that choice.
During the first two years of the Covid-19 pandemic, mortgage rates fell to record lows. Many people who bought homes then, or earlier, are still carrying rates at roughly one-third of today’s levels. That keeps monthly payments more manageable and leaves room to cover expenses such as renovations or college tuition without tapping equity.
- Rising interest rates make a second loan much more expensive than the current first mortgage.
- Growing economic uncertainty is also encouraging consumers to preserve their low-cost debt structure.
How do regional differences shape the market outlook?
Home equity has increased nationwide, but the picture varies widely from state to state. Equity is stronger in Western and Northeastern states, where faster home-price gains have widened the gap even further.
- In Hawaii and California, average homeowner equity was calculated at more than $600,000.
- In Massachusetts, it was more than $400,000.
- In Louisiana, Oklahoma and Iowa, average equity was just above $100,000.
By contrast, home values fell in some areas, including Texas, Minnesota, Colorado, Maryland and Washington, DC. That decline also reduced equity. Even so, the share of mortgages that are underwater — meaning the loan balance is higher than the home’s value — remained low nationwide at 2.1%.
"""
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.