
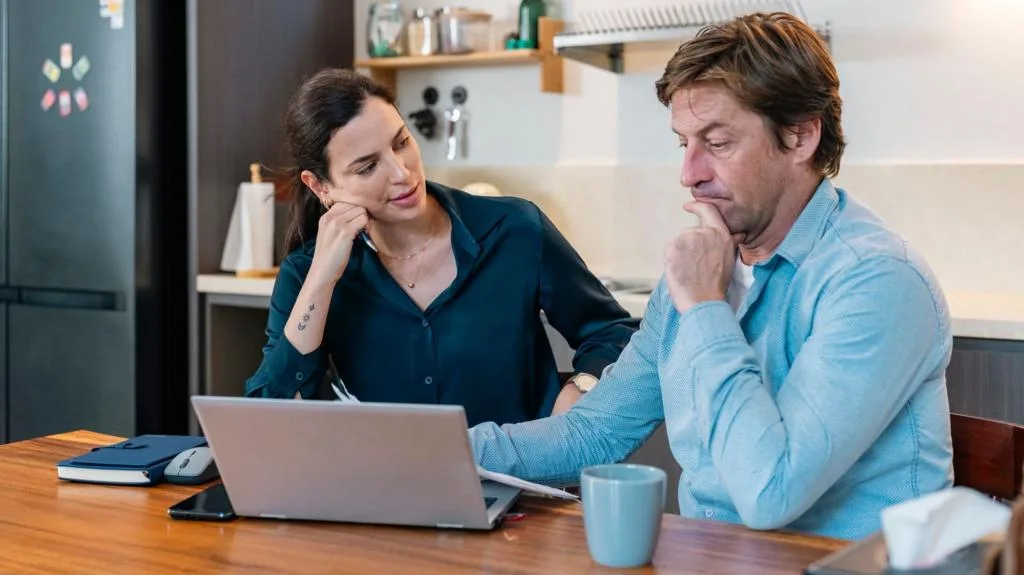
Average rate hits its highest level in three years
In the UK, the five-year fixed mortgage rate for new deals has risen to 6% for the first time in three years. Financial data provider Moneyfacts also said the average two-year fixed mortgage rate climbed to 5.98%. The recent increases are directly affecting both first-time buyers and borrowers preparing to refinance at the end of their fixed-rate deals.
Since the beginning of September, about 1,500 mortgage products priced below 5% have disappeared from the market. The trend shows that lower-cost options are shrinking quickly and that refinancing conditions are becoming tougher for households.
What is driving the rise in rates?
The increase in home loan costs has been driven by higher funding costs for lenders. The report says rising inflationary pressures, expectations for interest rates and higher government borrowing costs have pushed banks to reprice loans upward.
Wider global economic uncertainty deepened by the war in Iran is also being cited among the factors adding to the cost of mortgage offers. This suggests that risk sentiment in international markets is feeding through into housing finance as well.
- Five-year fixed mortgage: 6%
- Two-year fixed mortgage: 5.98%
- Products withdrawn from below 5%: about 1,500
What does it mean for fixed-rate borrowers?
With fixed-rate mortgage products, the rate does not change over the term of the deal; when the term ends, the borrower must choose a new package. Since a large share of homeowners and buyers use this type of loan, rising average rates could affect monthly payment plans for a broad group.
A move to the 6% threshold means a greater risk of higher monthly payments, especially for households coming up for renewal. The sharp drop in the number of cheaper products is also narrowing consumers’ options and reducing their room to negotiate.
"""
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.