
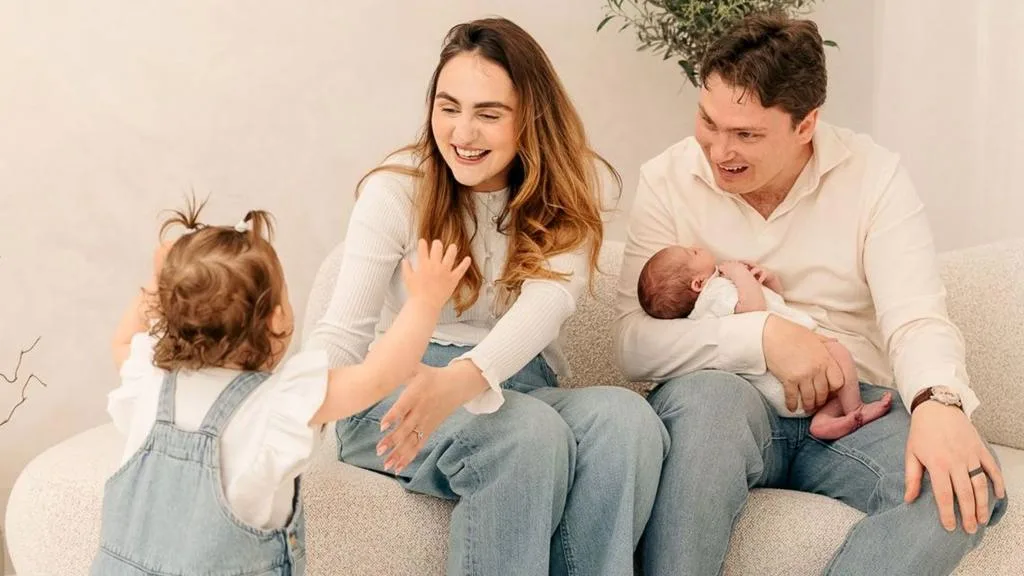
Child pension funds are taking up more room in family budgets
Junior SIPP accounts, known as child pension funds, are drawing growing interest from more families in the United Kingdom. Richard and Caitlin Brain, who live in Swansea in South Wales, are paying in £50 a month each for their two children, who are 20 months and 5 months old.
Under current UK private pension rules, the money can only be accessed by the children at age 57. That means the couple’s older child will be able to access the funds in 2082, and the younger child in 2083.
The family has also opened Junior ISA savings accounts for their children alongside the pension accounts. They are putting £60 a month into each of those accounts, creating a separate pot that can be used at age 18 for earlier needs such as education, starting a business or a housing deposit.
Tax relief and compound returns are boosting interest
The Junior SIPP system was introduced in 2001. Up to £2,880 a year can be paid into these accounts, with a £720 government tax top-up lifting the total to £3,600.
Industry data also points to a marked rise in demand. Investment platform Hargreaves Lansdown said the number of accounts opened in the 12 months to April 2026 was 2.5 times higher than in the same period a year earlier. Fidelity said account numbers have more than tripled since December 2023.
According to Fidelity pensions specialist Jemma Slingo, if £50 a month is invested from birth and tax relief is added, a family would contribute a total of £10,800 over 18 years. That could grow to about £135,000 by retirement age, highlighting the impact of starting early and the power of compound returns.
Key trade-offs for families
- Junior ISA accounts, which can be accessed at 18, stand out for short-term needs.
- For families aiming for long-term security, a pension account in a child’s name offers tax advantages.
- But regular contributions can mean cutting back on household spending.
Budget pressures and similar moves abroad
The Brain couple says they set aside a total of £220 a month for their children’s accounts, on top of a further £200 a month they contribute to their own private pensions and savings. The picture shows that long-term investing for children can only be sustained by being more careful with day-to-day spending.
A similar approach can be seen in the United States. Under the Trump Accounts plan announced in July by US President Donald Trump, families, friends and employers can contribute up to $5,000 a year per child. Unlike the UK model, the money can be accessed from age 18, but withdrawals before age 59.5 may be subject to tax and a possible 10% penalty.
The consensus among experts is that pension saving for children can provide a strong head start. Even so, they recommend considering these products only after parents have first balanced their own retirement planning and emergency savings.
"""
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.