
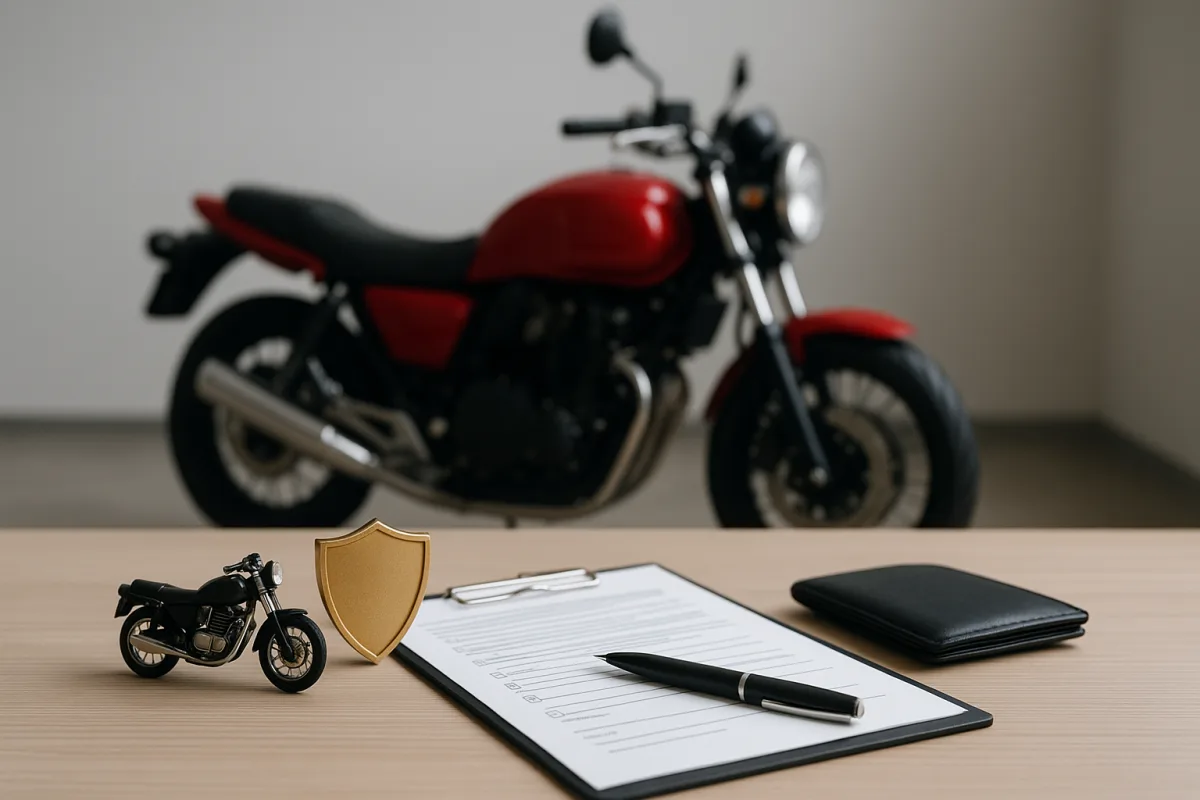
Main factors affecting motorcycle insurance premiums
When calculating a motorcycle insurance premium, insurers do not rely on a single criterion. Insurance companies assess the rider’s risk profile, the motorcycle’s features and the policy’s coverage together. For that reason, even two vehicles in the same segment can receive different insurance premium quotes.
In general, the main pricing factors are:
- The rider’s age and riding experience
- Claim history and previous policy records
- The motorcycle’s brand, model, age and engine size
- The vehicle’s intended use and annual usage intensity
- The selected coverages, deductibles and additional protections
Why is the rider profile considered important?
In premium calculations, the rider’s background is seen as decisive in understanding the expected level of risk. Having a new licence, using the motorcycle frequently or having a prior claims record can lead to different outcomes in insurers’ assessments. On the other hand, a steady policy history and a low claims tendency may help produce more balanced quotes in some cases.
Claim history and riding experience
In insurance, past claims records are treated as an important reference. Previous accidents, theft or similar risks can affect the price of a new policy. Likewise, the risk analysis for experienced riders and for users who are new to traffic may also differ.
How the motorcycle is used and where it is parked
Using the motorcycle for daily commuting, courier work or long-distance travel can change the risk assessment. Where the vehicle is parked at night, whether there is access to a covered parking area and how often it is used in heavy traffic may also be taken into account indirectly. These factors are especially important in terms of theft and damage risk.
How do vehicle features and coverage affect the price?
Traffic insurance and comprehensive insurance do not serve the same purpose, so their premium structures are different. Mandatory traffic insurance covers damage that may be caused to third parties, while comprehensive insurance is a broader policy that can also cover risks related to the motorcycle owner’s own vehicle. As coverage expands, the policy price can naturally change as well.
The motorcycle’s technical structure and market value
The vehicle’s age, spare parts cost, repair difficulty and market value can all influence the premium. High-performance models, bikes with expensive parts or models considered more exposed to theft may be assessed differently. Added accessories and special equipment may also require separate disclosure in some policies.
Points to consider when choosing a policy
- Review the coverage and exclusions, not just the price.
- Do not add unnecessary optional packages if you do not need them.
- Check which services are provided in the event of a claim.
- When comparing quotes, make sure they offer the same level of coverage.
In the end, the price of motorcycle insurance is determined not by the vehicle alone, but by a combination of many risk factors. To choose the right policy, it is important to focus not only on the lowest quote but also on the scope of protection provided.
Comments (0)
No comments yet. Be the first to comment.
Write a Comment
Yorum yazmak için giriş yapın. Üyelik ücretsiz; yorumunuz editör onayından sonra yayımlanır.